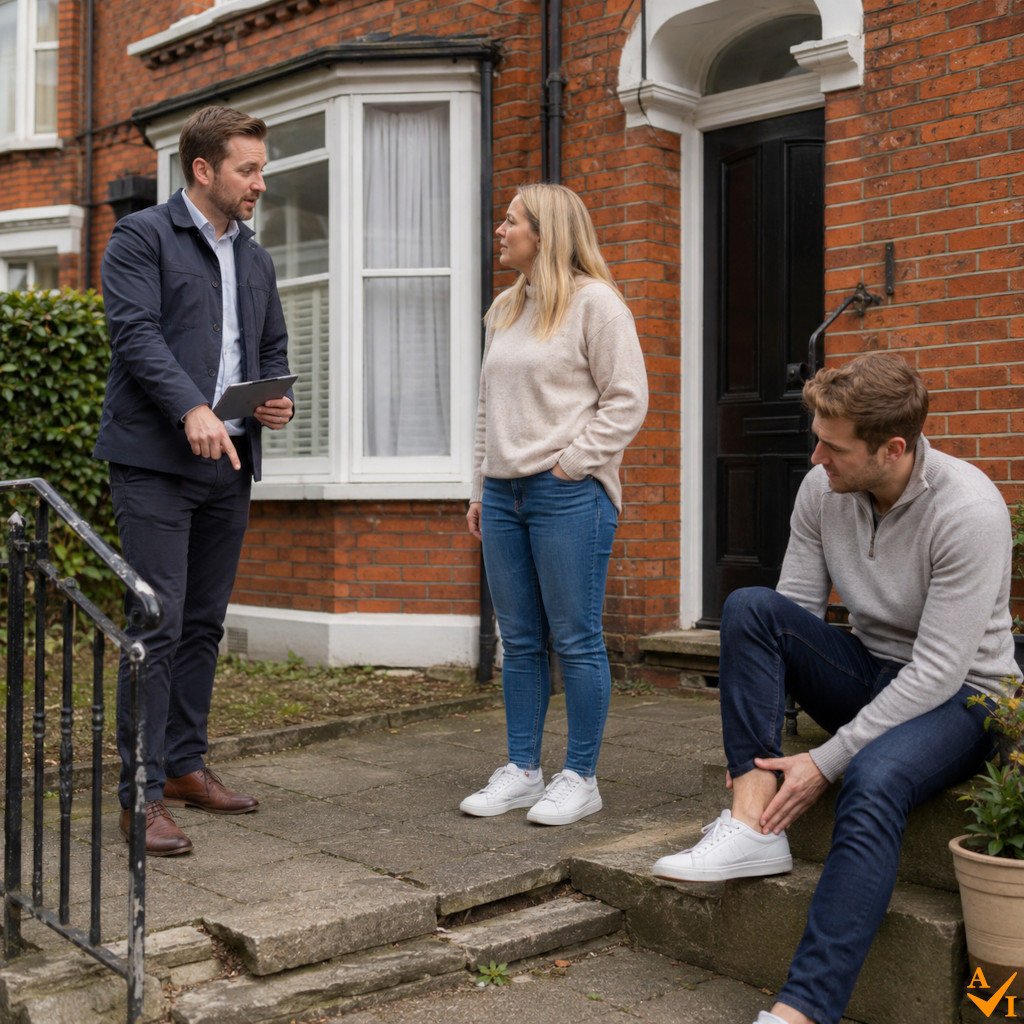
Being a landlord is a juggling act, balancing property maintenance with tenant relations. But even the most well-kept rental can experience unforeseen accidents. Imagine a tenant slipping on a loose step or a visitor tripping over a damaged path. Suddenly, you could be facing a compensation claim. This is where public liability insurance becomes your best ally, providing essential protection and peace of mind.
Understanding Public Liability Insurance
Public liability insurance is your safety net, covering landlords if someone is injured or their property is damaged due to hazards in the rental home. It takes care of legal expenses and potential compensation, shielding landlords from financial and reputational damage. For instance, if a tenant’s guest is injured by a faulty handrail, they could claim negligence against you. Without adequate cover, costs can escalate quickly, even if the incident wasn’t entirely your fault.
Why It’s Crucial
A standard building insurance policy might not automatically include public liability protection, making it essential to verify your coverage. Some mortgage lenders even require it for buy-to-let loans, recognising its importance in safeguarding your property and finances. It’s not just for major accidents; even minor incidents like water damage to a neighbour’s flat can lead to claims. Public liability ensures these are managed professionally and efficiently.
Peace of Mind for Landlords
Think of public liability insurance as part of your property’s safety net. Coupled with regular maintenance and clear communication with tenants, it minimises risk and stress. Being a landlord means managing both bricks and people. With the right protection in place, you can focus on running your property responsibly, knowing you’re covered if the unexpected happens. And remember, at Bond Residential, we’re here to support you every step of the way.